Personal Bankruptcy Laws 2026: 3 Key Changes for Filers
Significant amendments to personal bankruptcy laws in 2026 are poised to introduce crucial changes affecting eligibility, asset protection, and dischargeable debts for individuals seeking financial relief.
As we approach 2026, the landscape of personal finance continues to evolve, bringing with it notable shifts in legislation. For those navigating financial distress, understanding the upcoming changes to personal bankruptcy laws in 2026: 3 key changes affecting filers is not just beneficial, but critical. These modifications could significantly alter the path to debt relief, influencing everything from initial eligibility to the ultimate discharge of obligations. Let’s delve into these pivotal updates to help you prepare for what lies ahead.
Understanding the Evolving Bankruptcy Landscape
The realm of personal bankruptcy is rarely static, with laws and regulations frequently updated to reflect economic realities and societal needs. These changes are designed to balance the interests of debtors seeking a fresh start and creditors aiming for fair repayment. The impending alterations in 2026 are no exception, representing a concerted effort to refine the bankruptcy process.
These adjustments often stem from various factors, including shifts in economic policy, lobbying efforts, and judicial interpretations. For individuals contemplating bankruptcy, staying informed about these developments is paramount. A clear understanding can empower filers to make strategic decisions, optimize their outcomes, and navigate the complex legal framework with greater confidence.
The Rationale Behind Legislative Updates
Legislative bodies periodically review bankruptcy codes to address emerging financial challenges and close loopholes. This proactive approach ensures the system remains relevant and effective in an ever-changing economic environment. The 2026 changes are a direct response to current economic trends and an attempt to streamline the process for both filers and the courts.
- Economic Stability: Laws are updated to promote broader economic stability by ensuring fair treatment for debtors and creditors.
- Consumer Protection: New provisions often aim to enhance protections for vulnerable consumers, preventing predatory practices.
- System Efficiency: Revisions can simplify complex procedures, making the bankruptcy system more efficient and accessible.
Ultimately, these legislative updates are intended to foster a more equitable and functional system. They underscore the importance of continuous adaptation in legal frameworks to serve the needs of the population effectively. Understanding this broader context helps in appreciating the specifics of the upcoming changes.
First Key Change: Stricter Means Test Criteria
One of the most impactful changes expected in 2026 revolves around the means test, a crucial component for determining eligibility for Chapter 7 bankruptcy. This test, designed to prevent abuse of the system, assesses a debtor’s income against the median income in their state. The upcoming modifications are anticipated to introduce stricter parameters, potentially limiting access for some individuals.
The revised means test might incorporate new calculations for disposable income or adjust the median income thresholds more frequently. This could mean that individuals who previously qualified for Chapter 7 may find themselves directed towards Chapter 13, which involves a repayment plan rather than a complete discharge of debts. Such a shift would necessitate a re-evaluation of financial strategies for many prospective filers.
Impact on Chapter 7 Eligibility
The implications of a stricter means test are significant, particularly for those on the cusp of eligibility. A primary concern is that more individuals might be pushed into Chapter 13, which, while offering debt relief, requires a commitment to a multi-year repayment plan. This can be a more burdensome option for debtors already struggling financially.
- Increased Chapter 13 Filings: A potential rise in Chapter 13 cases as more debtors fail the Chapter 7 means test.
- Higher Attorney Fees: Chapter 13 cases often involve more complex legal processes, potentially leading to increased attorney fees.
- Longer Repayment Periods: Debtors might face extended periods of financial obligation under Chapter 13 plans.
These changes underscore the importance of early financial planning and seeking legal counsel well in advance of a potential filing. Understanding the nuances of the updated means test will be crucial for determining the most appropriate bankruptcy chapter and maximizing the chances of a successful outcome. The goal remains to provide a fresh start, but the pathway to that start may become more challenging for some.
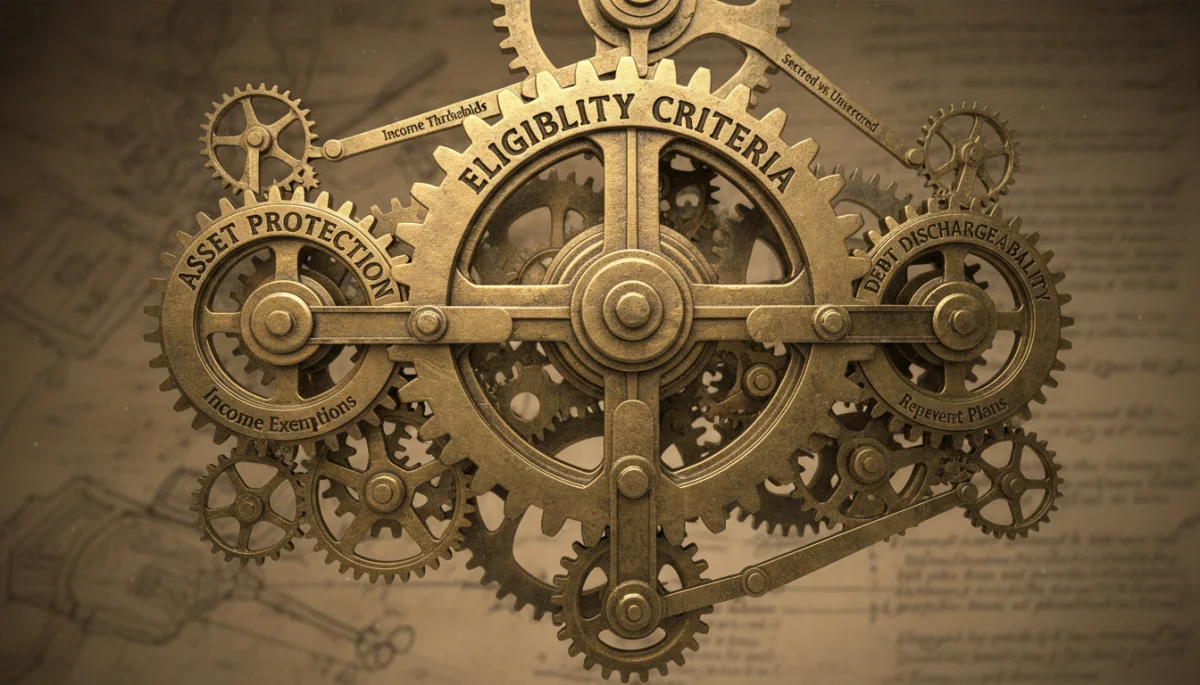
Second Key Change: Enhanced Asset Protection Measures
Another significant development in the 2026 personal bankruptcy laws focuses on enhanced asset protection. Historically, debtors have been concerned about losing valuable assets during bankruptcy proceedings. The new legislation aims to provide more robust exemptions, allowing filers to retain a greater portion of their property, thereby facilitating a more stable post-bankruptcy recovery.
These enhanced protections could include increased exemption limits for homesteads, vehicles, and personal property, or even the introduction of new categories of exempt assets. Such changes would be a welcome relief for many, reducing the fear of complete financial devastation and encouraging more individuals to seek bankruptcy relief when truly necessary, knowing they won’t lose everything.
Expanded Exemption Categories
The expansion of exemption categories is a key aspect of these new measures. This means that a wider range of assets, or higher values of existing exempt assets, will be protected from liquidation. For instance, tools of trade, retirement accounts, and even certain types of insurance policies might see their protected values increase substantially.
- Higher Homestead Exemptions: Allowing debtors to keep more equity in their primary residence.
- Increased Vehicle Exemptions: Protecting a greater value of vehicles essential for work or transportation.
- Broader Personal Property Protections: Safeguarding more household goods, furnishings, and personal effects.
These enhanced asset protection measures are designed to provide a more compassionate and realistic approach to bankruptcy, ensuring that individuals can emerge from the process with the foundational elements necessary to rebuild their lives. It represents a move towards recognizing the importance of a fresh start that isn’t entirely stripped bare of personal belongings.
Third Key Change: Modifications to Dischargeable Debts
The third pivotal change in personal bankruptcy laws in 2026 concerns modifications to dischargeable debts. This area of bankruptcy law determines which debts can be eliminated through the bankruptcy process and which cannot. The upcoming adjustments could alter the types of debts that are eligible for discharge, impacting the overall effectiveness of bankruptcy for some filers.
While certain debts like student loans and child support typically remain non-dischargeable, the new legislation might introduce nuances for other categories. For example, there could be changes regarding the dischargeability of certain tax debts, fines, or even specific types of consumer credit. These modifications will require careful consideration and understanding to maximize the benefits of filing.
New Categories and Exceptions
The potential introduction of new categories of dischargeable or non-dischargeable debts could significantly influence a debtor’s financial recovery. For instance, certain medical debts might become easier to discharge, or conversely, new restrictions could be placed on discharging specific types of business-related debts. These changes are often aimed at addressing evolving economic behaviors and societal priorities.
- Student Loan Review: Potential for slight modifications in the very stringent rules surrounding student loan forgiveness under specific hardship criteria.
- Tax Debt Adjustments: Possible changes to the look-back periods or conditions under which certain tax debts can be discharged.
- Consumer Credit Regulations: New stipulations regarding the dischargeability of debts incurred through specific types of high-interest or predatory lending.
These modifications to dischargeable debts highlight the dynamic nature of bankruptcy law. Filers will need to pay close attention to these specifics, as they directly impact which financial burdens can be shed and which will remain. The goal is to ensure the law remains fair while preventing abuse, but the practical implications for individuals can be profound.
Navigating the New Legal Landscape for Filers
With these significant changes on the horizon for personal bankruptcy laws in 2026, prospective filers must adopt a proactive approach. Understanding the intricacies of the stricter means test, enhanced asset protection, and modified dischargeable debts is paramount. This new legal landscape demands careful planning and informed decision-making to ensure the best possible outcome.
Engaging with experienced legal counsel becomes even more critical under these new regulations. A qualified bankruptcy attorney can provide tailored advice, help navigate the updated eligibility criteria, and strategize on asset protection and debt discharge. Their expertise will be invaluable in interpreting the new statutes and applying them to individual circumstances.
Proactive Steps for Debtors
For anyone considering bankruptcy in the near future, taking proactive steps now can make a substantial difference. This includes gathering all relevant financial documentation, understanding current debt obligations, and exploring all available debt relief options. The earlier one prepares, the better equipped they will be to adapt to the new legal framework.
- Financial Assessment: Conduct a thorough review of all income, assets, and liabilities.
- Legal Consultation: Seek advice from a bankruptcy attorney to understand how the new laws might apply.
- Debt Management Exploration: Consider alternatives to bankruptcy, such as debt consolidation or credit counseling, if appropriate.
By taking these steps, debtors can position themselves to effectively respond to the upcoming changes. The goal is not just to file for bankruptcy, but to achieve a sustainable financial recovery, and these new laws are designed to shape that journey. Preparedness is the key to successfully navigating this evolving legal environment.
Future Outlook and Long-Term Implications
The changes to personal bankruptcy laws in 2026 are not merely isolated adjustments; they represent a broader trend in how financial distress is managed within the legal system. These modifications will likely have long-term implications for consumer credit, lending practices, and the overall economic health of individuals and communities. The aim is to create a more resilient financial ecosystem.
Over time, these legislative shifts could influence how creditors assess risk, potentially leading to adjustments in interest rates and loan availability. For debtors, the experience of filing for bankruptcy might become more structured, with a greater emphasis on rehabilitation and financial education. The ongoing evolution of these laws reflects a continuous effort to strike a balance between providing relief and maintaining fiscal responsibility.
Adapting to a Changing Financial World
The ability to adapt to these legal changes will be crucial for both individuals and financial institutions. As the economic landscape continues to shift, so too will the mechanisms designed to manage financial hardship. These 2026 updates are a testament to that ongoing adaptation, signaling a future where financial resilience is increasingly prioritized.
- Credit Market Adjustments: Lenders may adjust their criteria based on the new bankruptcy provisions.
- Consumer Behavior: Debtors may become more cautious with credit due to stricter bankruptcy pathways.
- Financial Literacy: Increased emphasis on financial education to help individuals avoid future financial crises.
Ultimately, these legislative developments are part of a larger conversation about economic justice and stability. They aim to refine the process of financial recovery, making it more equitable and effective in the long run. Understanding these broader implications helps in appreciating the significance of each individual change and its potential impact on personal financial journeys.
| Key Change | Brief Description |
|---|---|
| Stricter Means Test | New criteria may limit Chapter 7 eligibility, potentially redirecting more filers to Chapter 13 repayment plans. |
| Enhanced Asset Protection | Increased exemption limits for assets like homesteads and vehicles, allowing debtors to retain more property. |
| Modified Dischargeable Debts | Adjustments to which debts can be eliminated, potentially affecting tax debts, fines, or specific consumer credit. |
Frequently Asked Questions About 2026 Bankruptcy Laws
While the means test is expected to be stricter, it will not make Chapter 7 impossible. It might, however, direct more individuals towards Chapter 13. Consulting a bankruptcy attorney is crucial to assess your specific eligibility under the new criteria.
Enhanced asset protection means you may be able to retain more of your personal property, such as your home equity, vehicle, and household goods, preventing their liquidation during bankruptcy proceedings. This provides a more stable foundation for your fresh start.
Student loans typically remain non-dischargeable, requiring an ‘undue hardship’ test. While the 2026 laws may introduce minor nuances, significant changes to student loan dischargeability are generally rare. Always discuss with a legal professional.
The decision to file for bankruptcy is highly personal and depends on your current financial situation. It’s essential to weigh the potential benefits and drawbacks of filing now versus waiting, considering how the new laws might affect your specific case. Seek expert legal advice.
Reliable information can be found through official government websites, accredited legal aid societies, and experienced bankruptcy attorneys. Always verify sources to ensure accuracy and relevance to your jurisdiction and specific circumstances.
Conclusion
The upcoming changes to personal bankruptcy laws in 2026 signify a crucial evolution in the mechanisms designed to help individuals navigate financial distress. From stricter means testing to enhanced asset protections and modified dischargeable debts, these adjustments will undoubtedly reshape the bankruptcy landscape. For anyone considering this path to financial recovery, proactive engagement with these new regulations and seeking expert legal guidance will be indispensable. Understanding these shifts is not just about compliance, but about empowering yourself to make informed decisions that lead to a more secure financial future.