Federal Reserve Policy 2026: Impact on Your Wallet
Understanding the Federal Reserve’s policy in 2026 is crucial for navigating its impact on interest rates, inflation, and ultimately, your financial well-being.
As we look ahead, understanding Federal Reserve Policy in 2026: Anticipating Moves and Their Effect on Your Wallet becomes paramount. The decisions made by the Fed ripple through every corner of the economy, directly influencing everything from mortgage rates to the cost of everyday goods. Preparing for these potential shifts is key to safeguarding your financial future.
Understanding the Federal Reserve’s Mandate in 2026
The Federal Reserve, often simply called the Fed, operates with a dual mandate: to foster maximum employment and maintain price stability. These two objectives are the guiding stars for all monetary policy decisions, and 2026 will be no exception. The challenge lies in balancing these goals, especially when economic conditions pull in different directions.
In 2026, the Fed will likely continue to navigate a complex economic landscape, influenced by both domestic and global factors. Its primary tools—interest rates, quantitative easing or tightening, and forward guidance—will be deployed strategically to achieve its mandate. The effectiveness of these tools hinges on market perception and broader economic responses.
The Dual Mandate Explained
Maximum employment doesn’t mean zero unemployment, but rather the lowest level of unemployment that can be sustained without igniting inflation. Price stability, on the other hand, typically refers to a low and stable inflation rate, often targeted around 2%. Achieving both simultaneously can be a delicate act, requiring constant vigilance and adaptability.
- Maximum Employment: Aiming for a healthy labor market where everyone who wants a job can find one at fair wages.
- Price Stability: Keeping inflation in check to preserve the purchasing power of the dollar.
- Financial Stability: A broader, informal mandate to ensure the resilience of the financial system.
The Fed’s communication strategy, known as forward guidance, will play a critical role in shaping market expectations for 2026. Clear and consistent messaging about future policy intentions can help reduce uncertainty and guide economic behavior. Conversely, ambiguous signals can lead to market volatility.
Ultimately, the Fed’s success in 2026 will be measured by its ability to steer the economy towards its dual mandate while maintaining confidence in its leadership. This requires a deep understanding of economic indicators and a willingness to adjust course as new data emerges. The implications for individual wallets will be significant, depending on how effectively these goals are met.
Anticipating Interest Rate Movements in 2026
Interest rates are arguably the most direct and impactful tool of Federal Reserve policy. The federal funds rate, the benchmark interest rate, influences everything from consumer loans to business investments. Predicting its trajectory in 2026 requires a careful analysis of current economic trends and the Fed’s forward-looking statements.
Several factors will likely dictate the Fed’s approach to interest rates. These include inflation pressures, labor market strength, and global economic conditions. Each of these elements can shift rapidly, making precise predictions challenging, but general trends can be anticipated.
Key Factors Influencing Rates
Inflation will remain a central concern. If inflation persists above the Fed’s 2% target, the likelihood of rate hikes increases. Conversely, a significant slowdown in inflation could pave the way for rate cuts. The labor market’s health also provides crucial insights into economic momentum. A robust job market might give the Fed more room to tighten, while weakness could prompt easing.
- Inflation Data: Consumer Price Index (CPI) and Personal Consumption Expenditures (PCE) will be closely watched.
- Labor Market Reports: Unemployment rates, job growth, and wage inflation will inform decisions.
- Global Economic Outlook: International economic stability and growth rates can influence Fed policy.
The Fed’s balance sheet will also be a factor. The size and composition of the Fed’s asset holdings can influence long-term interest rates. Any adjustments to quantitative tightening (reducing the balance sheet) or easing (expanding it) will have implications for market liquidity and borrowing costs.
For your wallet, interest rate movements in 2026 will directly affect borrowing costs for mortgages, auto loans, and credit cards. Savers might see better returns on deposits if rates rise, while borrowers could face higher monthly payments. Staying informed about these potential shifts is essential for making smart financial decisions.
The Impact of Inflation on Your Purchasing Power
Inflation, the rate at which the general level of prices for goods and services is rising, is a critical component of the Federal Reserve’s focus. In 2026, the Fed’s success in managing inflation will directly translate into the purchasing power of your dollar. High inflation erodes savings and makes everyday life more expensive, while stable inflation allows for predictable economic planning.
The sources of inflation can be diverse, ranging from supply chain disruptions to strong consumer demand. The Fed’s challenge is to identify the root causes and apply appropriate policy responses without stifling economic growth. This balancing act is crucial for maintaining a healthy economy.
Understanding Inflationary Pressures
In 2026, we might see a continuation of global supply chain adjustments, geopolitical events, and energy price volatility, all of which can contribute to inflationary pressures. Domestic factors, such as wage growth and consumer spending patterns, will also play a significant role. The Fed will be evaluating these elements closely to project future inflation trends.
- Supply Chain Resilience: How global supply chains adapt to disruptions will influence prices.
- Energy Costs: Fluctuations in oil and gas prices directly impact transportation and production costs.
- Wage-Price Spiral: The potential for rising wages to fuel higher prices, and vice versa.
The Fed employs various measures to gauge inflation, with the Personal Consumption Expenditures (PCE) price index being its preferred metric. This index provides a comprehensive look at consumer spending patterns, helping the Fed understand underlying inflationary trends. Consumer expectations about future inflation also heavily influence current spending and saving behaviors.
For your wallet, managing inflation in 2026 means being strategic with your spending and investments. Consider inflation-protected securities or real assets if inflation remains elevated. Budgeting carefully and seeking out value will be more important than ever to maintain your standard of living.
Quantitative Tightening and Its Economic Implications
Beyond adjusting interest rates, the Federal Reserve also utilizes quantitative tightening (QT) or quantitative easing (QE) to influence the economy. In 2026, the focus is likely to remain on QT, which involves reducing the Fed’s balance sheet by letting maturing bonds roll off without reinvestment. This process effectively removes liquidity from the financial system.
The goal of QT is to further tighten financial conditions, complementing interest rate hikes in the fight against inflation. However, QT is a less precise tool than interest rate adjustments, and its full effects can be harder to predict. Understanding its potential implications is vital for anticipating market behavior.
How Quantitative Tightening Works
When the Fed reduces its balance sheet, it decreases the demand for government bonds and other securities, which can push up long-term interest rates. This, in turn, can affect mortgage rates, corporate borrowing costs, and overall economic activity. The pace and magnitude of QT will be key considerations for the Fed in 2026.
- Reduced Liquidity: Less money flowing into the financial system, potentially increasing borrowing costs.
- Impact on Bond Yields: Higher yields on government bonds can make other investments less attractive.
- Market Volatility: QT can sometimes lead to increased volatility in financial markets as liquidity shifts.
The Fed’s communication regarding QT will be critical. Any unexpected shifts in the pace or duration of balance sheet reduction could trigger market reactions. Policymakers will likely aim for a predictable and measured approach to avoid unnecessary disruption.
For your wallet, the effects of quantitative tightening in 2026 might be indirect but significant. Higher long-term rates could impact the housing market, making mortgages more expensive. It could also affect investment returns, particularly in bond markets. Diversifying your portfolio and consulting with a financial advisor can help mitigate potential risks.
Geopolitical Factors and Global Economic Influence
The global economy is interconnected, and the Federal Reserve does not operate in a vacuum. Geopolitical events and the economic performance of other major nations can significantly influence U.S. monetary policy decisions in 2026. From trade tensions to international conflicts, external factors can create both opportunities and challenges for the Fed.
Global economic growth, or lack thereof, can impact demand for U.S. exports, influencing domestic employment and inflation. Currency fluctuations, driven by international dynamics, can also affect the competitiveness of U.S. goods and services, making the Fed’s job more complex.
External Shocks and Policy Responses
In 2026, potential geopolitical flashpoints, such as ongoing conflicts or trade disputes, could introduce new uncertainties. These events can disrupt supply chains, increase commodity prices, and dampen investor confidence. The Fed will need to carefully assess how these external shocks might impact the U.S. economy and adjust its policy stance accordingly.
- Trade Relations: Changes in international trade agreements or tariffs can impact inflation and economic growth.
- Global Growth: A slowdown in major economies can reduce demand for U.S. products and services.
- Currency Movements: A stronger dollar can make U.S. exports more expensive and imports cheaper, affecting inflation.
The actions of other central banks, such as the European Central Bank or the Bank of Japan, will also be on the Fed’s radar. Coordinated or divergent monetary policies among major global economies can amplify or offset the effects of the Fed’s own decisions. International financial stability is a shared responsibility.
For your wallet, global economic influences in 2026 might manifest through higher prices for imported goods, shifts in investment opportunities, or even job market changes if export-oriented industries are affected. Staying aware of global headlines and their potential economic ripple effects is a smart financial habit.
Preparing Your Wallet for 2026: Practical Steps
With the potential shifts in Federal Reserve policy in 2026, taking proactive steps to prepare your personal finances is crucial. While the future is uncertain, a well-planned financial strategy can help you navigate potential challenges and capitalize on opportunities. This involves reviewing your budget, debt, investments, and savings.
Financial resilience is about anticipating changes and building a buffer. Small adjustments made now can have a significant impact on your financial well-being throughout 2026 and beyond. Consider these practical steps to fortify your financial position.
Actionable Financial Strategies
Start by reviewing your budget to identify areas where you can save or cut unnecessary expenses. High interest rates can make debt more burdensome, so prioritizing debt reduction, especially on variable-rate loans, is a wise move. Building an emergency fund remains a cornerstone of financial security.
- Budget Review: Identify and trim non-essential spending to free up cash.
- Debt Management: Focus on paying down high-interest debt, particularly variable-rate credit cards.
- Emergency Fund: Aim for 3-6 months of living expenses saved in an easily accessible account.
On the investment front, consider diversifying your portfolio to include assets that perform well in different economic environments. Speaking with a financial advisor can provide personalized guidance based on your risk tolerance and financial goals. Rebalancing your portfolio periodically can help ensure it aligns with your long-term objectives.
Finally, stay informed. Regularly checking reliable financial news sources and understanding the Federal Reserve’s communications can help you make timely decisions. Being proactive and adaptable will be your greatest assets in navigating the economic landscape of 2026 and protecting your wallet.
| Key Point | Brief Description |
|---|---|
| Fed’s Dual Mandate | Focus on maximum employment and price stability (2% inflation target). |
| Interest Rate Outlook | Influenced by inflation, labor market, and global conditions; impacts borrowing costs. |
| Inflation Management | Key for purchasing power; affected by supply chains, energy, and demand. |
| Personal Finance Prep | Budgeting, debt reduction, and diversified investments are crucial. |
Frequently Asked Questions About Federal Reserve Policy in 2026
The Federal Reserve’s primary goal in 2026, as always, is to achieve maximum employment and maintain price stability. This dual mandate guides all its monetary policy decisions to ensure a healthy and stable U.S. economy, balancing job growth with controlled inflation.
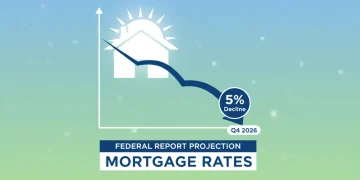
If interest rates rise in 2026, new mortgages and variable-rate mortgages will likely become more expensive. Conversely, if rates fall, borrowing costs could decrease. Fixed-rate mortgages secured before any rate changes would generally remain unaffected.
Quantitative tightening (QT) is when the Fed reduces its bond holdings, withdrawing money from the economy. In 2026, QT could lead to higher long-term interest rates, affecting mortgage rates, bond yields, and potentially increasing market volatility, indirectly impacting your investments and borrowing.
To protect savings from inflation in 2026, consider investments like Treasury Inflation-Protected Securities (TIPS), real estate, or a diversified stock portfolio. Maintaining a strong emergency fund in a high-yield savings account can also help, though it may not fully outpace high inflation.
Absolutely. Global events such as geopolitical conflicts, international trade dynamics, and economic performance in other major countries will significantly influence the Fed’s policy decisions in 2026, impacting U.S. inflation, employment, and overall financial stability. The Fed constantly monitors these external factors.
Conclusion
The Federal Reserve’s policy decisions in 2026 will undoubtedly shape the economic landscape and directly influence your financial well-being. By understanding the Fed’s dual mandate, anticipating potential shifts in interest rates and inflation, and recognizing the impact of quantitative tightening and global factors, you can better prepare your wallet. Proactive financial planning, including diligent budgeting, debt management, and strategic investing, will be essential to navigate the year successfully. Staying informed and adaptable will empower you to make sound decisions, ensuring resilience in the face of evolving economic conditions.