Healthcare Reform Update: 7 Key Changes to ACA Subsidies Mid-2026
Starting mid-2026, significant reforms to Affordable Care Act subsidies will introduce 7 key changes impacting eligibility criteria, premium tax credit calculations, and overall healthcare affordability for millions of Americans across the United States.
As mid-2026 approaches, millions of Americans are bracing for significant shifts in their healthcare landscape. The Healthcare Reform Update: 7 Key Changes to Affordable Care Act Subsidies Starting Mid-2026 signals a pivotal moment for health insurance affordability and accessibility, prompting a closer look at what these modifications entail for individuals and families nationwide.
Understanding the Affordable Care Act and Subsidies
The Affordable Care Act (ACA), often referred to as Obamacare, revolutionized healthcare access in the United States. Its core objective was to make health insurance more accessible and affordable for Americans who couldn’t obtain coverage through their employers or government programs like Medicare or Medicaid.
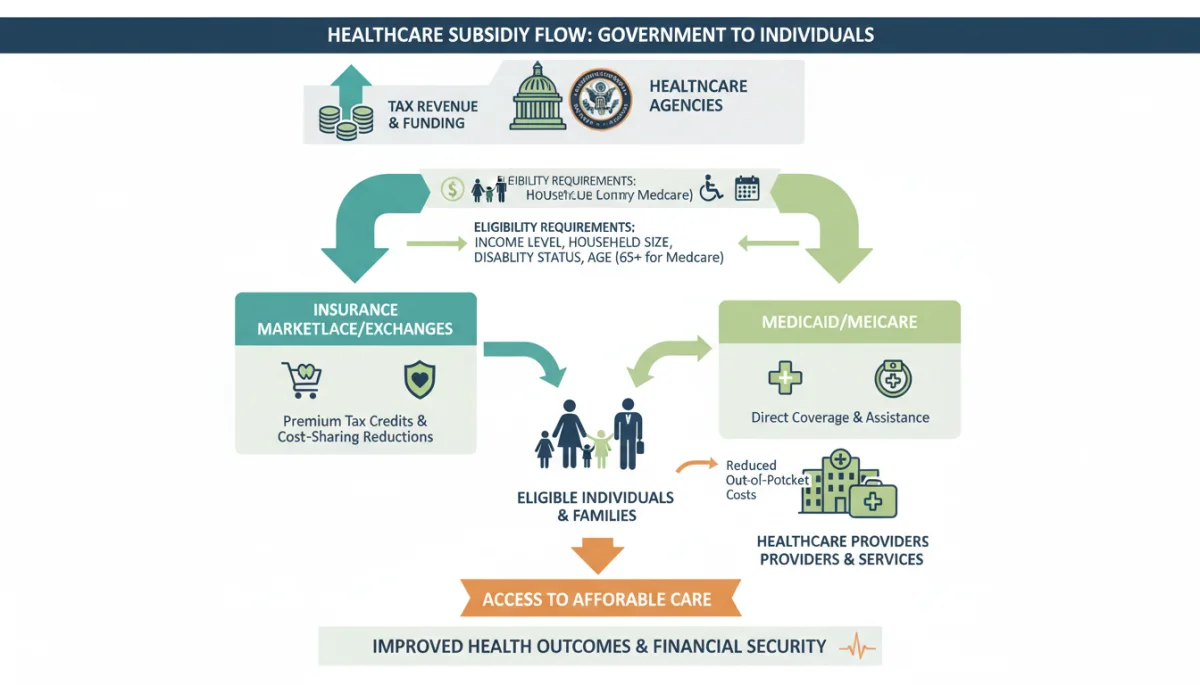
A cornerstone of the ACA’s affordability measures is its system of subsidies. These financial aids, primarily in the form of premium tax credits, help eligible individuals and families lower their monthly insurance premiums. The amount of subsidy an individual receives is typically based on their income, household size, and the cost of health plans available in their area through the Health Insurance Marketplace. Understanding these foundational elements is crucial before delving into the upcoming changes.
Premium Tax Credits Explained
Premium tax credits are refundable tax credits that can be used immediately to lower your monthly health insurance premium costs. You can choose to have these credits paid directly to your insurance company each month, or you can claim the full amount when you file your federal income tax return.
- Eligibility for premium tax credits depends on your household income relative to the federal poverty level (FPL).
- The credits are designed to cap your premium contributions at a certain percentage of your income.
- Adjustments are made based on changes in income or household size throughout the year.
Beyond premium tax credits, the ACA also offers Cost-Sharing Reductions (CSRs) to eligible individuals. These CSRs help lower out-of-pocket costs like deductibles, co-payments, and co-insurance. While distinct from premium subsidies, both are vital components of the ACA’s framework for making healthcare more affordable.
In essence, the ACA’s subsidy structure has been a lifeline for many, enabling them to secure health coverage that might otherwise be out of reach. The upcoming reforms in mid-2026 will undoubtedly adjust the parameters of this vital support system, necessitating a detailed examination of each change to prepare effectively.
Change 1: Revised Income Thresholds for Eligibility
One of the most impactful adjustments slated for mid-2026 concerns the income thresholds that determine eligibility for ACA subsidies. Currently, subsidies are primarily available to individuals and families with incomes between 100% and 400% of the federal poverty level (FPL). The upcoming reform is expected to recalibrate these percentages, potentially expanding or narrowing the pool of eligible beneficiaries.
This revision could mean that some individuals who were previously ineligible might now qualify for assistance, while others who currently receive subsidies might find their eligibility altered or even eliminated. The precise new thresholds will be critical for millions to assess their future healthcare costs. Policymakers aim to refine the system to better target those most in need, responding to economic shifts and healthcare cost inflation.
Impact on Middle-Income Earners
Historically, middle-income earners have sometimes found themselves in a ‘coverage gap,’ earning too much for Medicaid but too little to afford unsubsidized marketplace plans. The revised income thresholds could specifically target this demographic.
- Potential for increased subsidy access for those just above the current 400% FPL cap.
- Risk of reduced subsidies for individuals whose incomes fall near the upper end of the revised scale.
- The changes will likely vary by state, given differences in FPL and cost of living adjustments.
The updated income criteria are not merely numerical adjustments; they reflect a broader strategy to fine-tune the ACA’s financial assistance. This could lead to a more equitable distribution of aid, ensuring that subsidies reach those who genuinely struggle to afford health insurance premiums. Understanding where your household income falls within the new FPL percentages will be the first step in determining your subsidy status post-2026.
Ultimately, these revised income thresholds are designed to adapt the ACA to current economic realities, ensuring that the subsidy system remains relevant and effective in promoting affordable healthcare access. Americans should closely monitor official announcements regarding these specific changes to understand their personal impact.
Change 2: New Calculation Methods for Premium Tax Credits
Beyond eligibility, the actual calculation of premium tax credits is set to undergo significant modifications starting mid-2026. These changes aim to refine how the government determines the level of financial assistance, potentially leading to different subsidy amounts even for those whose eligibility remains consistent. The current calculation method ties subsidies to the cost of the second-lowest-cost silver plan in a given area, with individuals expected to contribute a certain percentage of their income toward premiums.
The upcoming reforms may introduce new formulas or factors into this calculation, possibly incorporating regional healthcare costs more directly, or adjusting the percentage of income individuals are expected to contribute. This could result in a more granular and perhaps more equitable distribution of subsidies, but it also introduces complexity for consumers trying to estimate their future costs.
Factors Influencing New Calculations
Several elements could play a larger role in the new subsidy calculations:
- Geographic Cost Variations: Greater emphasis on the specific cost of healthcare services and insurance premiums in different regions.
- Age Adjustments: Potential modifications to how age impacts premium contributions and subsidy levels.
- Household Composition: Refinements in how household size and dependents are factored into income and subsidy calculations.
These new calculation methods are intended to make the subsidy system more responsive to individual circumstances and market dynamics. For consumers, this means that simply knowing their income and household size might no longer be sufficient to predict their subsidy amount. They will need to pay close attention to the detailed formulas released by the Department of Health and Human Services.
The objective behind these changes is to ensure that premium tax credits effectively reduce the burden of healthcare costs without over-subsidizing or under-subsidizing certain demographics. As such, understanding the updated methodology will be paramount for anyone relying on ACA subsidies.
Change 3: Enhanced Focus on Specific Demographics
The upcoming ACA subsidy reforms also signal an enhanced focus on providing targeted assistance to specific demographic groups that have historically faced greater barriers to affordable healthcare. This strategic shift aims to address persistent disparities in health coverage and outcomes, ensuring that the benefits of the ACA reach the most vulnerable populations more effectively. While the exact groups to receive enhanced focus are still being detailed, early indications suggest an emphasis on lower-income populations, rural communities, and potentially certain minority groups.
This targeted approach moves beyond a one-size-fits-all model, recognizing that healthcare affordability is not uniform across all segments of the population. By tailoring subsidy structures to meet the unique needs of these demographics, policymakers hope to close existing gaps in coverage and improve overall public health.
Potential Beneficiaries of Targeted Subsidies
The enhanced focus could translate into several benefits for identified groups:
- Increased financial assistance: Higher premium tax credits or more generous cost-sharing reductions.
- Expanded outreach programs: Dedicated resources to help specific communities navigate the Marketplace and enroll in plans.
- Tailored plan options: Development of insurance plans that better meet the specific health needs of these demographics.
This particular change represents a proactive step towards health equity within the ACA framework. For individuals belonging to these targeted demographics, it could mean a significant improvement in their ability to afford comprehensive health insurance. It’s crucial for advocacy groups and community leaders to disseminate information about these specific enhancements to ensure eligible individuals take full advantage of the updated support.
Ultimately, by prioritizing specific demographics, the ACA aims to build a more inclusive healthcare system where financial barriers are systematically reduced for those who need it most, fostering better health outcomes across the board.
Change 4: New Requirements for State Marketplace Participation
Another significant reform coming in mid-2026 involves new requirements for state-run health insurance marketplaces. Currently, states have some flexibility in how they operate their marketplaces, leading to variations in plan availability, enrollment processes, and consumer support. The upcoming changes are expected to introduce more standardized guidelines or enhanced performance metrics that states must meet to ensure consistent quality and accessibility nationwide.
These new requirements could range from stricter data reporting mandates to minimum standards for consumer assistance and technology infrastructure. The goal is to improve the overall efficiency and effectiveness of the marketplaces, making it easier for consumers to shop for and enroll in plans, regardless of their state of residence. This could also foster greater competition among insurers, potentially leading to more affordable options.
Implications for State-Run Marketplaces
The new requirements will compel state marketplaces to adapt and potentially invest in new systems:
- Standardized technology platforms: Ensuring a more uniform user experience across states.
- Enhanced consumer support: Mandating specific levels of assistance for enrollment and navigating plans.
- Improved data transparency: Requiring states to report more comprehensive data on enrollment, costs, and outcomes.
For consumers, these changes are largely positive, promising a more streamlined and reliable experience when seeking health insurance through the marketplace. It could also lead to greater clarity regarding plan comparisons and subsidy applications. States that already meet or exceed these new standards may see minimal impact, while others might need to undertake significant overhauls.
Ultimately, these new requirements underscore a commitment to strengthening the foundational infrastructure of the ACA, ensuring that the marketplaces function optimally as the primary gateway to subsidized health coverage for millions of Americans.
Change 5: Increased Scrutiny on Plan Affordability and Coverage
Starting mid-2026, there will be an increased scrutiny on the affordability and comprehensiveness of health plans offered through the ACA marketplace. This change is designed to ensure that even with subsidies, consumers are purchasing plans that genuinely provide adequate coverage without imposing excessive out-of-pocket costs. Historically, some plans, while seemingly affordable in terms of premiums, have come with very high deductibles or limited networks, making actual access to care challenging.
The new reforms aim to set clearer benchmarks for what constitutes an ‘affordable’ and ‘comprehensible’ plan, potentially leading to stricter criteria for plans to be listed on the marketplace. This could involve re-evaluating the actuarial value of plans, setting limits on out-of-pocket maximums relative to income, or enhancing requirements for network adequacy. The objective is to protect consumers from plans that offer little real benefit despite lower premiums.
What ‘Increased Scrutiny’ Means for Consumers
For consumers, this enhanced scrutiny translates into several key benefits:
- Better value for money: Plans offered are more likely to provide meaningful coverage and access to care.
- Reduced risk of ‘surprise’ costs: Lower likelihood of encountering unexpectedly high deductibles or co-pays.
- Clearer plan comparisons: Easier to understand the true costs and benefits of different plans.
This move reflects a commitment to the spirit of the ACA, which is not just about making insurance available, but making good insurance available. While it might lead to some plans being removed or redesigned, the overall impact is expected to be positive for consumers, ensuring that their healthcare dollars, whether subsidized or not, are spent on quality coverage.
In essence, increased scrutiny on plan affordability and coverage is a crucial step towards ensuring that the ACA delivers on its promise of providing comprehensive and accessible healthcare for all Americans, moving beyond mere enrollment figures to focus on the actual utility of the insurance plans.
Change 6: Expanded Role of Navigators and Enrollment Assistance
The upcoming ACA reforms for mid-2026 will also significantly expand the role and funding for ‘Navigators’ and other enrollment assistance programs. Navigators are individuals and organizations trained to help consumers understand their health insurance options, apply for financial assistance, and enroll in plans through the Health Insurance Marketplace. This expansion recognizes the critical role these resources play in helping individuals, especially those in underserved communities, navigate the complexities of healthcare enrollment.
The increased investment in these programs aims to improve consumer education, reduce enrollment barriers, and ensure that more eligible individuals successfully obtain coverage. This could involve more widespread outreach efforts, increased staffing, and enhanced training for Navigators to better address the diverse needs of the population.
Benefits of Enhanced Enrollment Assistance
The expanded role of Navigators offers several advantages:
- Improved access for vulnerable populations: Dedicated support for individuals who may lack internet access, language proficiency, or digital literacy.
- Higher enrollment rates: More people successfully enrolling in plans they understand and can afford.
- Better informed decisions: Consumers receiving personalized guidance to choose the best plan for their specific health needs and financial situation.
This change underscores the understanding that simply having a marketplace is not enough; active support is essential for effective utilization. By bolstering Navigator programs, the ACA aims to make the enrollment process less daunting and more accessible for everyone, especially as other subsidy changes come into effect. This human-centered approach is vital for ensuring that the benefits of the ACA reach every corner of the United States.
Ultimately, the expanded role of Navigators is a testament to the belief that informed consumers are empowered consumers, leading to a more robust and equitable healthcare system for all Americans.
Change 7: Streamlined Reporting and Verification Processes
The seventh key change to ACA subsidies starting mid-2026 involves a concerted effort to streamline reporting and verification processes. This reform aims to simplify the administrative burden for both consumers and government agencies, making it easier to apply for and maintain subsidy eligibility. Currently, the process of reporting income changes, household adjustments, and verifying information can sometimes be cumbersome, leading to delays or errors in subsidy calculations.
The upcoming changes are expected to introduce more integrated data systems, automated verification tools, and clearer guidelines for reporting life changes. The goal is to reduce paperwork, minimize discrepancies, and ensure that subsidies are accurately disbursed in a timely manner. This benefits consumers by providing greater certainty about their financial assistance and reduces the potential for repayment issues at tax time.
How Streamlining Benefits Consumers
A streamlined process translates into tangible advantages for individuals and families:
- Reduced administrative hassle: Less time spent on paperwork and more intuitive online tools.
- Faster processing of changes: Quicker adjustments to subsidies when income or household size changes.
- Fewer errors and repayment surprises: Greater accuracy in initial subsidy determinations, reducing the risk of owing money back to the IRS.
This focus on administrative efficiency is a critical evolution for the ACA. By making the backend processes smoother, the entire system becomes more user-friendly and reliable. It also allows government resources to be allocated more effectively, ensuring that the primary focus remains on providing affordable healthcare, rather than managing complex bureaucratic procedures.
In conclusion, the streamlining of reporting and verification processes is a practical yet impactful reform that will enhance the overall experience of participating in the ACA marketplace, ensuring that financial assistance is delivered efficiently and accurately to those who need it.
| Key Change | Brief Description |
|---|---|
| Revised Income Thresholds | Adjustments to income levels for subsidy eligibility, potentially expanding or narrowing access. |
| New Calculation Methods | Refined formulas for premium tax credits, impacting subsidy amounts. |
| Enhanced Demographic Focus | Targeted assistance for specific vulnerable populations to improve health equity. |
| Streamlined Processes | Simplified reporting and verification for easier subsidy application and management. |
Frequently Asked Questions About ACA Subsidies in 2026
Not necessarily. While some adjustments might be automatic based on new calculations, it’s crucial to proactively review your eligibility and potential new subsidy amount. The marketplace should provide updated information, and you may need to re-verify income or household details to ensure you receive the correct financial assistance.
The revised income thresholds could either expand or narrow eligibility. If your income falls within the new, potentially broader range, you might qualify for subsidies for the first time. Conversely, if your income is at the upper end of the current range, you might find your subsidy reduced or eliminated. Specific details will be released closer to mid-2026.
Stay informed by regularly checking official government sources like Healthcare.gov. Gather your financial documents, including income statements and tax returns, to accurately report your information. Consider consulting a Navigator or a certified insurance broker for personalized guidance on how the changes will impact your specific situation and plan choices.
The goal of the reforms is to improve the affordability and effectiveness of subsidies, not necessarily to increase costs for everyone. While some individuals might see their subsidy amounts change, the overall aim is to better target assistance and ensure plans offer better value. The impact will vary significantly based on individual circumstances and the specific changes in your area.
The most reliable and up-to-date information will be available on official government websites, particularly Healthcare.gov. You can also look for announcements from the Department of Health and Human Services (HHS) and state health insurance marketplaces as mid-2026 approaches. Reputable news outlets specializing in healthcare policy will also cover these developments.
Conclusion
The impending Healthcare Reform Update: 7 Key Changes to Affordable Care Act Subsidies Starting Mid-2026 marks a critical juncture for healthcare access and affordability across the United States. These reforms, encompassing revised income thresholds, new calculation methods, targeted demographic support, and streamlined processes, reflect a dynamic effort to adapt the ACA to evolving economic realities and population needs. For millions of Americans, understanding these changes is not merely an academic exercise but a practical necessity for securing and maintaining vital health coverage. Proactive engagement with official resources, diligent review of personal eligibility, and seeking expert guidance will be paramount in navigating this new landscape successfully, ensuring that the promise of affordable healthcare remains a reality.